
A bookkeeper records what happened in your business. An accountant interprets it, files the returns and helps you decide what to do next. A CPA is an accountant with a state license and the legal standing to represent you before the IRS. Most growing small businesses end up needing all three functions, though not always as three separate people.
This guide explains where the lines fall, what each role costs the market, when to hire each, and how to avoid paying for the wrong one.
TL;DR
- Bookkeepers keep the daily records accurate: transactions, reconciliations, invoices, payroll entries. They look backward.
- Accountants turn those records into financial statements, tax returns and planning. They look forward.
- CPAs are licensed accountants. Along with enrolled agents and attorneys, they hold unlimited representation rights before the IRS. A bookkeeper without those credentials does not.
- Hire a bookkeeper when the books eat your week. Bring in a CPA before big decisions, not in April.
- The cheapest setup that works is usually clean books plus a CPA who sees them during the year.
Table of Contents
- The short version: records versus interpretation
- What a bookkeeper does
- What an accountant does
- Where CPAs fit in
- The IRS representation gap
- Bookkeeper vs. accountant vs. CPA at a glance
- What the pay gap says about the work
- When you need a bookkeeper
- When you need an accountant or CPA
- Do you need both?
- What it looks like when the roles work together
- Our perspective: the ledger and the strategy belong together
- How to choose and what to ask
- Working with Elevate
- FAQ
- Sources
The short version: records versus interpretation
The distinction comes down to scope. One widely quoted line says all accountants are bookkeepers, but not all bookkeepers are accountants. Bookkeeping is the systematic record of what already happened. Accounting analyzes that record and plans from it.
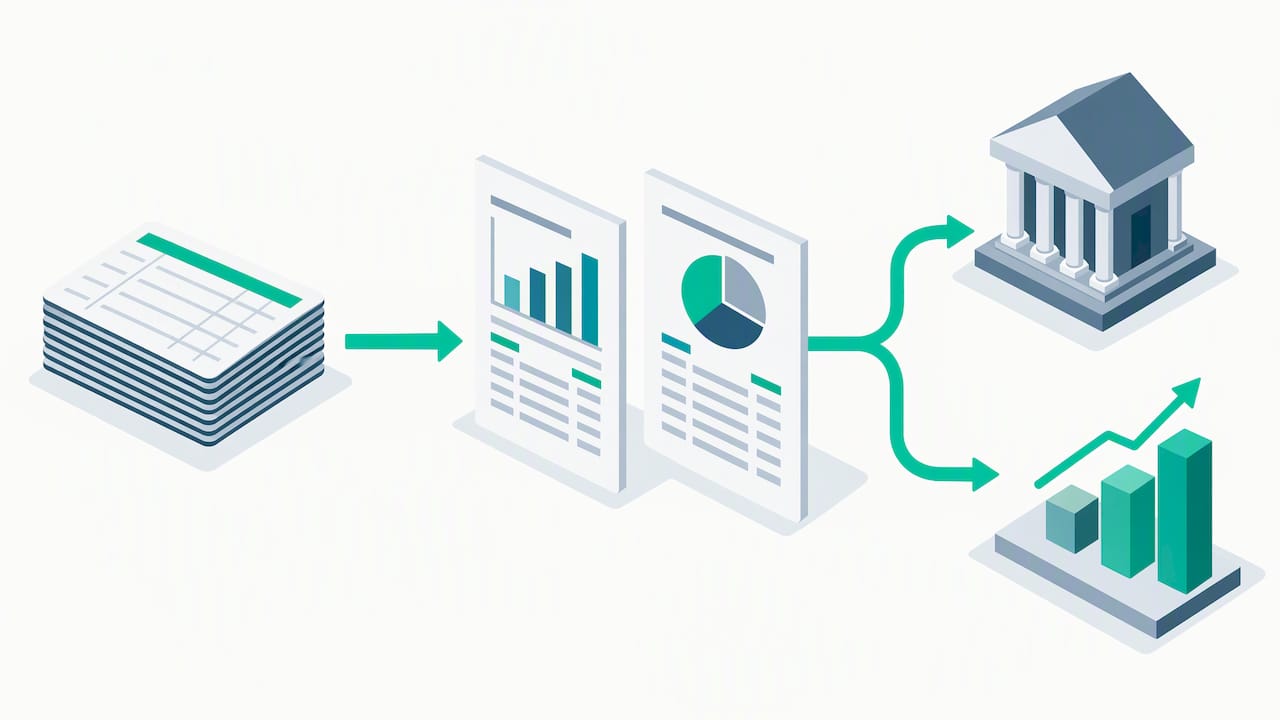
Think of it as a pipeline:
- Money moves through your business.
- The bookkeeper captures and categorizes every movement.
- The accountant checks the result, produces statements, prepares taxes and advises.
- You make decisions with numbers you can trust.
If step 2 is sloppy, step 3 is expensive. If step 3 never happens, you have tidy records and no strategy.
What a bookkeeper does
Bookkeepers handle the high-volume, detail-heavy work that has to happen every week or month:
- Recording and classifying daily transactions
- Reconciling bank and credit card accounts
- Sending invoices and tracking what customers owe
- Paying bills and tracking what you owe
- Entering payroll and keeping payroll records
- Producing basic reports, such as a profit and loss statement
The U.S. Bureau of Labor Statistics describes bookkeeping, accounting and auditing clerks as people who compute, classify and record data so organizations keep complete, accurate financial records. That is the job in one sentence.
Good bookkeeping is not clerical busywork. It is the raw material for every tax and financing decision you will make. For a closer look at how we approach it, see our page on bookkeeping services that help you plan ahead.
What an accountant does
Accountants work at a higher level. According to the AICPA, an accountant’s responsibilities can include recording transactions, preparing financial statements, and tax preparation and planning. In practice for a small business that means:
- Preparing balance sheets, income statements and cash flow statements
- Preparing and filing business and owner tax returns
- Planning taxes ahead of time, including entity choice, estimated payments and deductions
- Reviewing the books for errors and weak controls
- Advising on pricing, hiring, equipment purchases, financing and growth
Accountants often do some bookkeeping too, and plenty of small firms bundle both. The reverse is less common: a bookkeeper who also prepares tax returns, advises on entity structure and signs financial statements is really working as an accountant.
Where CPAs fit in
“Accountant” is a broad label. A certified public accountant is a narrower one: a licensed accountant who has passed the CPA Exam and met education and experience requirements. That license matters for three practical reasons.
- Standards. A license comes with ethics rules and continuing education, which you can verify with your state board.
- Depth. CPAs are trained for tax strategy, financial reporting and the complex questions that come with growth.
- Representation. This is the one most owners miss, and it gets its own section below.
If you searched for the difference between a CPA and a bookkeeper, the answer is the same as above, with a license added. A CPA can do bookkeeping. A bookkeeper cannot become a CPA by doing bookkeeping for longer.
The IRS representation gap
Here is the difference that shows up when something goes wrong. The IRS says any tax professional with a PTIN may prepare federal returns, but enrolled agents, CPAs and attorneys have unlimited representation rights. They can represent you on any matter, including audits, payment and collection issues, and appeals.
So if your bookkeeper’s records trigger a notice or an audit, a bookkeeper without one of those credentials cannot speak for you. You would need to hire someone who can, often under time pressure and often to untangle records that nobody reviewed. If you are weighing a bookkeeper against a CPA purely on price, count this exposure on the CPA side of the ledger.
Bookkeeper vs. accountant vs. CPA at a glance
| Bookkeeper | Accountant | CPA | |
|---|---|---|---|
| Main job | Record and reconcile transactions | Analyze, report, prepare taxes | Everything an accountant does, under a license |
| Time focus | Past and present | Present and future | Present and future |
| Typical outputs | Categorized ledger, reconciliations, basic reports | Financial statements, tax returns, advice | Statements, returns, tax strategy, representation |
| Credential | None required to use the title in general | Varies | State license after passing the CPA Exam |
| Represents you before the IRS | Not unless also an EA, CPA or attorney | Only if credentialed as above | Yes, unlimited rights |
| Best for | Keeping up with volume | Taxes and reporting | Tax planning, complex situations, financing |
What the pay gap says about the work
Salary data is a rough proxy for responsibility. As of May 2025, the BLS reports a median annual wage of $50,670 for bookkeeping, accounting and auditing clerks, against $83,680 for accountants and auditors. The gap reflects education, depth of skill and regulatory responsibility.
For you as a buyer, that translates into a simple rule of thumb: pay bookkeeper rates for bookkeeping work and accountant rates for judgment. A CPA reconciling bank accounts is an expensive way to get data entry. A bookkeeper choosing your entity structure is a cheap way to get an expensive mistake.
When you need a bookkeeper
The clearest signal is time. One accounting software glossary suggests hiring help when you spend more than five hours a week on financial tasks or need monthly reports. Other signs:
- You are behind on reconciling accounts, sometimes by months
- You are not sure what your profit was last month
- You pay bills late or chase invoices from memory
- You have employees and payroll records are scattered
- Your tax preparer keeps asking for missing statements
If any of that sounds familiar, our payroll processing services and QuickBooks consulting can take most of that work off your plate.
When you need an accountant or CPA
The same source puts the point where a CPA becomes essential at annual revenue approaching $500,000, or when you face complex regulatory, investment or multi-state tax decisions. Treat that as a guideline, not a line in the sand. Some owners need a CPA on day one. Consider one now if:
- You are choosing between an LLC taxed as-is and an S corporation. Our explainer on LLC versus S corporation taxes shows what changes.
- You pay quarterly estimates and are never sure of the amount. See quarterly estimated tax payments made clear.
- You want to lower self-employment tax in ways that hold up. Start with how to lower self-employment taxes legally.
- You are about to buy property, equipment or another business.
- You need financing, or a lender or investor has asked for statements.
- You received an IRS or state notice.
Financing and investors need accounting, not just bookkeeping
Real estate investors and startups often assume accounting exists to file taxes. Lenders and investors want financial statements that follow GAAP or another recognized reporting standard, and producing them is accounting work. The AICPA lists preparing financial statements among core accountant tasks. If you expect to raise money or refinance, bring in an accountant before you need the statements, so the ledger is built to produce them. Our guides on financial reporting for business owners and startup accounting system setup explain how.
Do you need both?
Usually, yes, and sooner than you think. A practical way to decide:
| Your situation | Likely fit |
|---|---|
| Solo owner, simple income and expenses, a few transactions a week | Software plus a CPA for the annual return and a planning check-in |
| Growing business, 5+ hours a week on the books | Bookkeeper for the monthly work, CPA for taxes and planning |
| Employees, multiple income streams or rental properties | Bookkeeper plus a CPA who sees the numbers during the year |
| Raising capital, buying property, or facing an audit | CPA involved now, with clean books underneath |
| Regulated or specialized industry | A firm that knows your industry’s tax and reporting rules |
The money mistake is rarely hiring the wrong title. It is hiring one and expecting the other’s output. A bookkeeper cannot give you tax strategy, and a CPA who only sees a shoebox of receipts in April can only report what already happened.
What it looks like when the roles work together
The AICPA’s guidance on choosing a CPA notes that CPAs work with clients all year, not just during tax season, covering future tax planning and business issues. That is the model that saves money. A workable annual rhythm:
- Monthly: books closed and reconciled, reports reviewed.
- Quarterly: estimated taxes checked, cash flow reviewed, payroll compliance confirmed.
- Before big purchases or hires: a short planning conversation with your CPA.
- Fourth quarter: year-end moves, while they can still change the result.
- Filing season: returns prepared from books that are already clean.
Our article on cash flow forecasting for small businesses pairs well with step 2.
Our perspective: the ledger and the strategy belong together
We are a CPA firm in Medford, and we see the same pattern with new clients. Owners treat bookkeeping as the whole financial solution. Clean books tell you what happened. They do not tell you why, or what to do about it.
The opposite problem is just as common: a business hands a CPA a pile of receipts in April and asks for the lowest bill. By then the big decisions are made and most tax levers are gone. Tax law keeps changing, and the value of a proactive CPA is influencing decisions during the year rather than filing forms afterward. That is the same point the AICPA’s tax practice leadership makes in its guidance on what accountants do.
That is why we connect bookkeeping, payroll, tax planning and advisory work instead of treating them as separate jobs. When the person building your tax strategy also understands how your ledger is structured, nothing gets lost between handoffs, and the books are ready for the CPA’s work from day one. It also means that if you ever face an IRS question, the CPA responding already knows your records.
Pick the structure that fits your size, but do not wait for a crisis to involve a CPA.
— Justin Ash, CPA
How to choose and what to ask
Whoever you hire, ask these before signing:
- Is there a license? Ask whether the person is a CPA, enrolled agent or attorney, and check the license with the state board. The IRS also keeps a public directory of credentialed preparers.
- What exactly is included? Monthly close, payroll, sales tax, tax planning and year-end work are separate items. Get them in writing.
- Who talks to me during the year? Year-round access is the difference between planning and reporting.
- What do you know about my industry? Real estate, startups and cannabis each carry their own rules and reporting needs.
- What software do you use? Your books should live in a system you can see, ideally one your CPA can also see.
- What happens if I get a notice? The answer should name who responds and whether they have representation rights.
Because scope differs from business to business, we do not publish flat prices. We scope each engagement to what your business needs.
Working with Elevate
If you want one team for the whole picture, we offer accounting and bookkeeping, tax planning and preparation, payroll and business consulting for small businesses, startups, real estate investors and cannabis operators. Specialized pages cover real estate accounting and cannabis accounting. To see how a CPA should work with a local business, read what a Medford CPA should do for your business, or contact us through the site to book a consultation.
FAQ
Is an accountant higher than a bookkeeper?
In scope and credentials, usually yes. Accountants interpret data, prepare statements and taxes, and advise. Bookkeepers record and organize the data. Neither is better in absolute terms, since the work is different and a business needs both functions.
What can an accountant do that a bookkeeper cannot?
An accountant can prepare financial statements, plan taxes and advise on decisions. A CPA, enrolled agent or attorney can also represent you before the IRS in audits, collections and appeals. A bookkeeper without one of those credentials cannot.
Can a CPA do my bookkeeping?
Yes. Many CPA firms offer bookkeeping alongside tax and advisory services. The trade-off is cost: you want routine entry done at bookkeeper rates and CPA time spent on planning and review. A firm that offers both can split the work that way.
Which pays more, accounting or bookkeeping?
Accounting, on average. BLS data for May 2025 puts median pay for accountants and auditors well above that of bookkeeping clerks, at $83,680 versus $50,670 a year.
Should I hire a bookkeeper or an accountant first?
If you are drowning in transactions, start with a bookkeeper. If you are making large decisions about entity choice, financing or property, start with a CPA. In either case, get the CPA involved before year-end so planning can still change the outcome.
Sources
- Bookkeeping vs. Accounting: What’s the Difference? (Forbes Advisor)
- Bookkeeping, Accounting, and Auditing Clerks (U.S. Bureau of Labor Statistics)
- What does an accountant do? (AICPA & CIMA)
- CPA explained: Careers, ethics, and why licensure is the gold standard (AICPA & CIMA)
- Understanding tax return preparer credentials and qualifications (IRS)
- What is the Difference Between Bookkeeping and Accounting (Xero)
- How to Choose a CPA (AICPA & CIMA)